AI Bot vs. Phone Intake for Melbourne Mortgage Brokers
AI lead qualification for mortgage brokers vs phone intake: what a bot can collect, what only a licensed broker can do under ASIC rules, and costs.
A referral comes in at 7:15pm. You call back the next morning and spend 25 minutes on the same questions you asked yesterday's lead: PAYG or self-employed, income, deposit, debts, residency, what they want to buy. Half the calls end with "you're not quite ready yet". The other half are the reason you are in business, and you cannot tell which is which until you have spent the time.
Short answer: For Melbourne mortgage brokers, an AI lead qualification bot should handle the first fact-gathering conversation and booking, any time of day, and a phone call should handle everything that needs advice. The bot collects facts and records them; it must not suggest particular loans or lenders, because that is credit assistance, which sits with you under ASIC rules.
What should an AI bot handle, and what must stay with the broker?
The bot gathers and records facts; the broker advises. That line is not just good practice, it follows the regulatory line.
Under the National Credit Act, credit assistance includes suggesting that a consumer apply for, or remain in, a particular credit product, and ASIC's Regulatory Guide 203 notes that tools which tailor a product comparison to a particular consumer are more likely to be credit assistance than generic information. Since 1 January 2021, mortgage brokers giving credit assistance must also act in the consumer's best interests and prioritise the consumer's interests where there is a conflict (s158LA and s158LE, explained in RG 273).
So a well-designed intake bot is built to stay on the fact-finding side of that line:
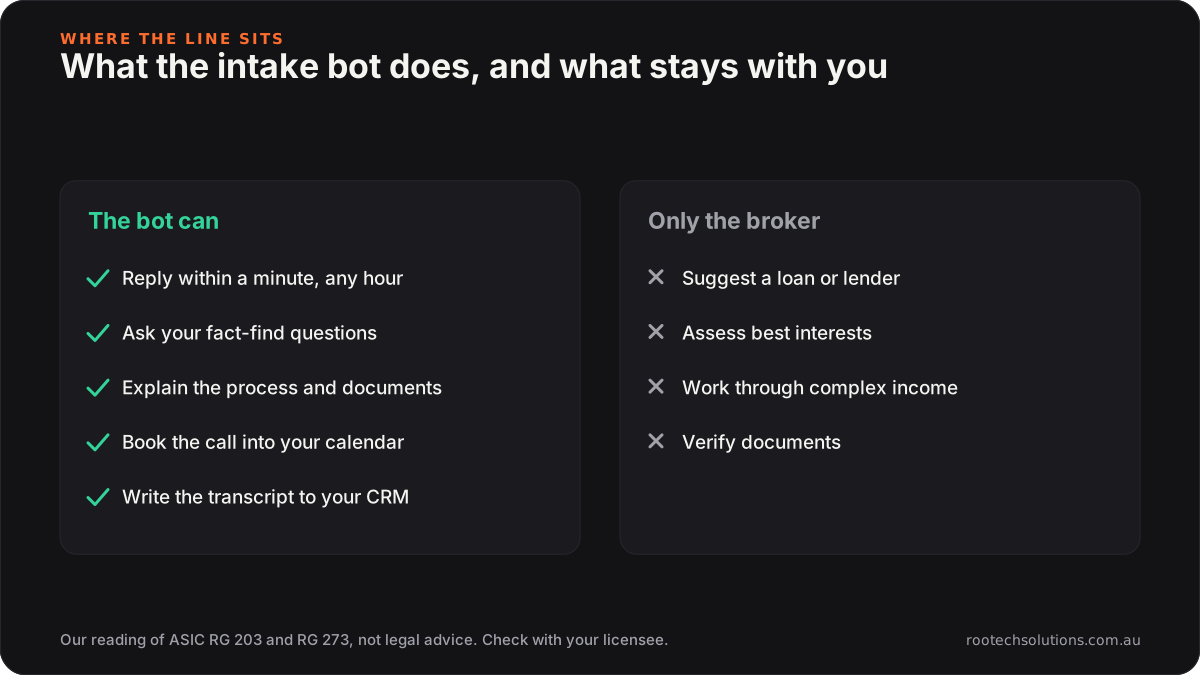
Caption: Draw the line once, in the bot's rules, and it holds on every conversation at every hour.
This is our reading of ASIC's published guidance, not legal advice; check the design with your licensee or compliance adviser before launch, the same way you would check new marketing.
Does ASIC let a client give their details to a bot?
ASIC's guidance anticipates it. RG 273 notes that consumers may give their instructions face to face, by phone, by email, or by entering information on an online platform. It also notes that what consumers disclose at first is often not enough to work out what is in their best interests, which is exactly why the bot is the start of intake, not the end of it.
The other useful point in RG 273 is record keeping: ASIC expects brokers to keep records of the inquiries they make into a consumer's circumstances. A bot that writes every question, answer and timestamp into your CRM gives you a consistent, complete record of first contact, which is usually better than notes typed after a phone call.
How do an AI bot and phone intake compare?
| AI intake bot | Phone intake call | |
|---|---|---|
| First reply | Within a minute, any hour | Next business window |
| Data captured | The same fields every time, written to the CRM | Depends on who took the call |
| Handles complex income or credit history | Flags it and books a call | Yes, this is where the call earns its keep |
| Builds trust | Through speed and clarity | Through your voice and judgement |
| Suggests products or lenders | Never, by design | Yes, as licensed credit assistance |
| Your time per lead | A few minutes reviewing the summary | The full call |
| Cost | Fixed-price build plus low running costs | Your hours or a staff member's |
The useful way to read this table is not "which one" but "which part of intake". The bot takes the questions that have one right answer each. You take the conversation that needs judgement.
What does the hybrid intake look like in practice?
- Enquiry arrives from your website, a referrer link, or a Google or Facebook ad form.
- The bot replies by SMS or web chat within a minute, introduces itself as your automated assistant, and asks your fact-find questions: purchase or refinance, owner-occupied or investment, employment type and time in role, rough income and deposit, existing debts, residency.
- It answers process questions from your approved content: how broking works, what documents to have ready, whether you charge a fee, how long pre-approval usually takes with your process.
- It books a call into your calendar, and flags anything that needs care first: self-employed with a short ABN history, a past default, a guarantor, a complicated trust structure.
- You get a summary in your CRM before the call. If the facts are already gathered, a 25-minute intake call can become a shorter advice conversation; the time saved depends on how much of your current call is fact-finding.
Anything that sounds like hardship, distress or a complaint skips the bot's script and goes straight to you.
Is off-the-shelf broker software enough?
Your CRM and aggregator tools already do a lot. Broker CRMs such as Salestrekker, Mercury and MyCRM handle fact finds, client portals, document collection and the path to lodgement, and many include online fact-find forms (check what your aggregator provides). If your problem is document chasing after the first call, start there.
What they do not usually do is hold a live, two-way conversation with a new lead at 9pm, answer their questions, and book them in. A custom AI integration sits in front of your existing CRM to do that one job, then writes everything into the CRM fields you already use. You do not change systems; you add a front door.
What does it cost, and how long does it take?
A fixed-price intake bot for a brokerage typically costs $2,000 to $5,000 to build when it covers one or two channels (web chat and SMS) and writes to one CRM and one calendar. More channels, multiple brokers' calendars or deeper CRM integration push it higher. Running costs are hosting, usually under $50 a month, plus AI usage of roughly $20 to $200 a month depending on lead volume, and SMS at your provider's rates. These are estimates.
Most builds are live in two to four weeks. The first week is the important one: your fact-find questions, approved answers, the hard rules (no product, rate or lender suggestions; no predictions about approval), the triggers that hand a lead straight to you, and a review by your licensee. Then the build, the CRM connection, and testing against your last few months of real enquiries.
For a fuller cost picture across a brokerage, see what Melbourne mortgage brokers pay for AI automation.
When should you stick with phone intake?
Stick with the phone when your leads are few and mostly warm. As a rule of thumb, if you see fewer than ten new enquiries a month, mostly from referrers who already trust you, and you can call each one back within the hour, the personal call is your advantage and a bot adds little.
The bot earns its place when volume or timing beats you: paid ads producing weekend spikes, a steady flow of after-hours enquiries, or a team where intake notes vary by who took the call. If clients' trust in AI is the worry, we looked at that directly in will mortgage clients trust AI with a loan application. For how fast follow-up works across other businesses, see AI lead agent vs email autoresponder.
Frequently asked questions
Can an AI bot tell a client what they can borrow?
It should not give a borrowing figure or say whether they will be approved. Those depend on a proper assessment and lender policy, and a number from a bot can set expectations you then have to walk back. The bot can explain what you will look at in the call and what documents help.
Where is client data stored, and is it secure?
In your CRM and in hosting accounts in your business's name, with access limited to your team. Financial details are sensitive, so the build should follow the Australian Privacy Principles, collect only what the first conversation needs, and never ask for documents or identity numbers in chat.
Will a bot put off first home buyers?
Some prefer a human voice from the start, so the bot should offer a call straight away to anyone who asks. Many first home buyers enquire late at night after a day of open inspections; a clear, instant reply that books them in often feels more helpful than waiting until morning.
Do I need my licensee's approval?
Check with them. Most licensees want to review client-facing scripts and automated communications, and the intake bot is both. Bringing them the question list and the hard rules early makes approval quicker.
Want to see where intake is costing you time?
We will look at how your enquiries arrive, how long intake takes and where leads drop off, and show you what a compliant intake bot would handle. Rootech is Melbourne-based (custom software in Melbourne). Book a free AI workflow audit; if you go ahead, the audit fee comes off your first project.