What Melbourne Mortgage Brokers Pay for AI Automation
AI automation for mortgage brokers: build and running costs in AUD, a payback that allows for settlement lag, and what the best interests duty rules out.
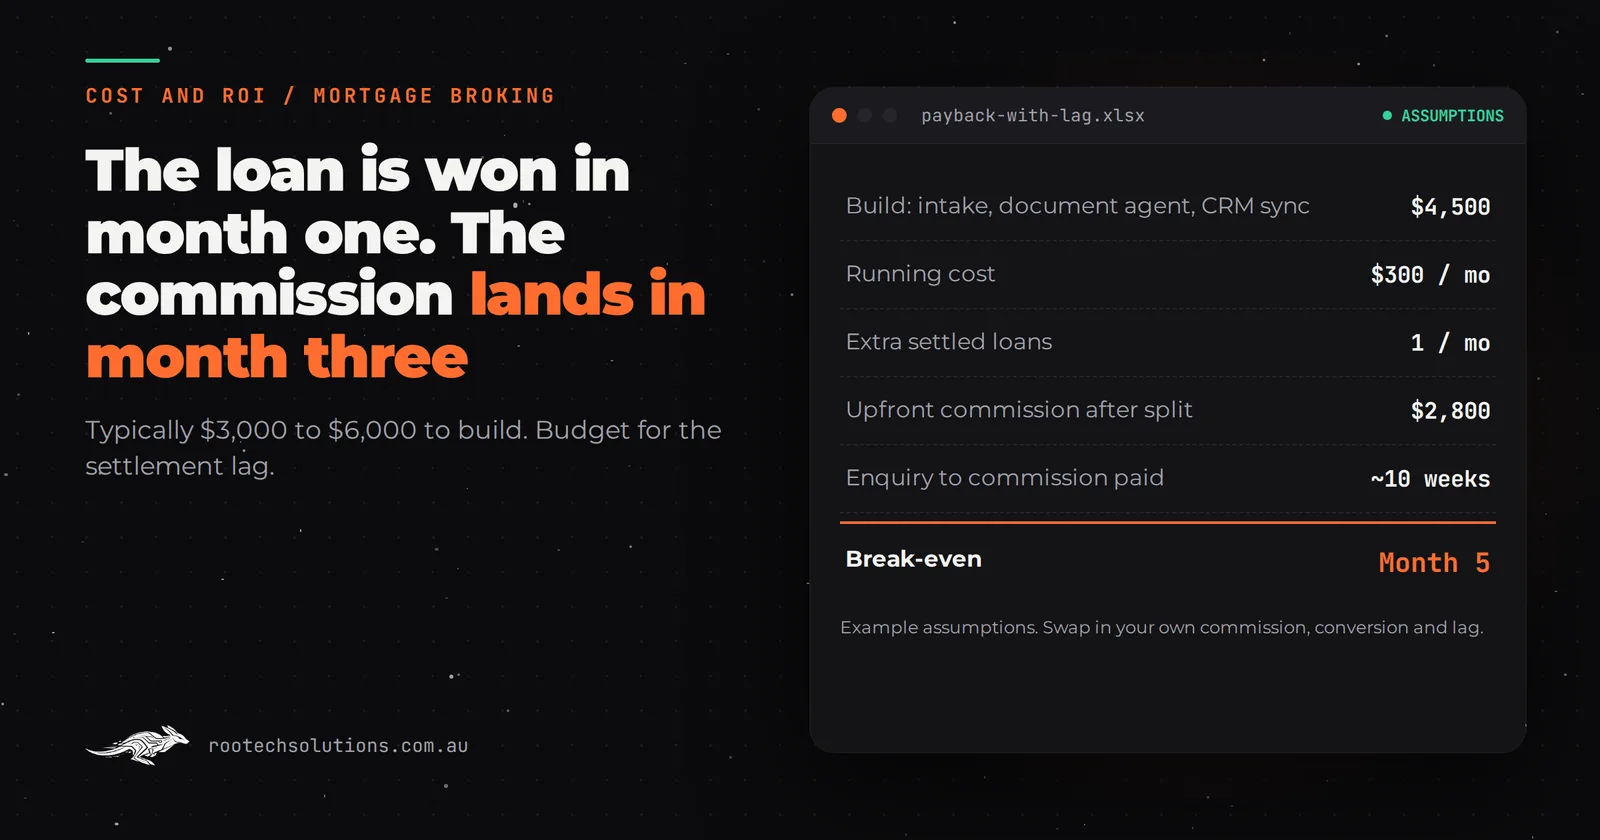
A broker does not get paid when a borrower says yes. The commission arrives after settlement, often two or three months after the enquiry that started it, and then flows through your aggregator. So when you ask what AI automation costs, the honest answer has to include when the money comes back, not just whether it does.
There is a second difference. Most of what a broker says to a borrower is regulated, which narrows what AI automation for mortgage brokers is allowed to do. The good news is that the most valuable work, intake and document chasing, sits comfortably inside the rules.
Short answer: AI automation for a Melbourne mortgage broker typically costs $3,000 to $6,000 to build and $150 to $450 a month to run. Because commission only arrives after settlement, a build that wins one extra loan a month usually breaks even around month five, not month one. It should collect information and documents, never suggest a lender or product.
Why is the payback slower for a broker than for a tradie?
Because the revenue lags the win. A plumber who answers a missed call is paid that week. A broker who wins a borrower in March may not see the upfront commission until settlement in May or June, and trail commission builds slowly after that.
That lag changes the maths in two ways:
- Cash goes out before it comes in. You pay for the build and two or three months of running costs before the first extra commission lands. Plan for that, especially as a sole broker.
- The win is easy to misattribute. By the time a loan settles, nobody remembers it started as a 9pm enquiry that got an instant reply. Tag every lead with its source in your CRM from day one, or you will never know whether the automation paid.
If your aggregator agreement claws back commission when a loan is refinanced or discharged early, use a slightly lower commission figure in your sum to allow for it.
What does AI automation for mortgage brokers cost?
A useful first build is a small set of connected pieces, priced as one fixed-price project. These are estimates:
- Instant intake, day or night: a web form, chat and missed-call text-back that collects the borrower's goal, timeframe, income type and deposit, and books a call into your calendar.
- Document collection agent: texts the borrower exactly what to upload (ID, payslips, bank statements, tax returns for self-employed borrowers), checks what arrived, flags anything missing, unreadable or out of date, and chases until the file is complete.
- Status updates: plain-language messages at each milestone (submitted, valuation booked, conditional approval, unconditional, settlement) so borrowers stop calling to ask.
- CRM sync: everything written into your broker CRM rather than retyped.
A focused intake and document flow for one broker typically lands around $3,000 to $4,000. A multi-broker office with CRM integration, status updates and an after-hours phone agent sits nearer $6,000. Running costs of $150 to $450 a month cover AI usage, SMS (still the channel borrowers answer fastest), a dedicated number, any per-minute voice agent and small changes. Hosting is usually under $50 of that.
How do I work out the payback with settlement lag?
Lay it out month by month. Every figure below is an assumption: replace it with your own conversion rate, your average upfront commission after the aggregator's share, and your typical enquiry-to-settlement time.
Assumptions: build $4,500; running $300 a month; one extra settled loan a month from leads you would otherwise have lost; $2,800 upfront commission per loan after the aggregator split; about ten weeks from enquiry to commission paid.
| Month | Cost this month | Commission in | Running position |
|---|---|---|---|
| 0 (build) | $4,500 | $0 | minus $4,500 |
| 1 | $300 | $0 | minus $4,800 |
| 2 | $300 | $0 | minus $5,100 |
| 3 | $300 | $2,800 | minus $2,600 |
| 4 | $300 | $2,800 | minus $100 |
| 5 | $300 | $2,800 | plus $2,400 |
| 6 | $300 | $2,800 | plus $4,900 |
Put another way: by month four you have spent $5,700 and received $5,600, and by month six you have spent $6,300 and received $11,200.
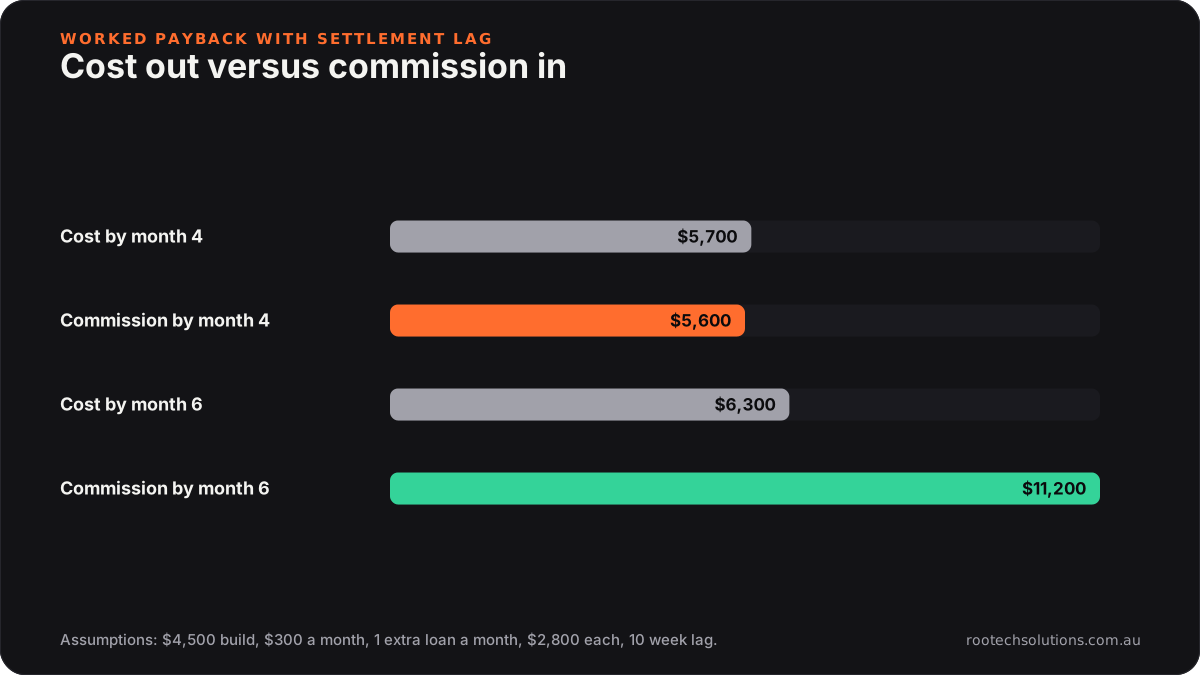
Caption: The automation starts winning loans in month one. The bank account only notices in month three.
The sum leaves out three things, all in your favour: trail commission on each extra loan, the hours you stop spending chasing payslips, and the borrowers who refer friends because the process felt organised. It also leaves out one risk: if your extra loans per month is closer to zero than one, the line never crosses. Count how many enquiries went unanswered for more than a few hours last quarter before you decide.
What can the AI say to a borrower, and what can it not?
It can gather information, explain your process, chase documents and book appointments. It should not suggest a particular lender or loan. From 1 January 2021 mortgage brokers have been required to act in the best interests of consumers and prioritise their interests when providing credit assistance, and ASIC sets out how it assesses that duty in Regulatory Guide 273.
ASIC's guidance on licensing (RG 203) treats suggesting that a consumer apply for a particular credit contract with a particular credit provider as credit assistance. An AI that replies at 9pm with "on your numbers, Lender X at this rate looks best" is doing exactly that, without the inquiries a broker must make. That is why the "instant rate quote" chatbot some vendors pitch is the wrong design for a broker.
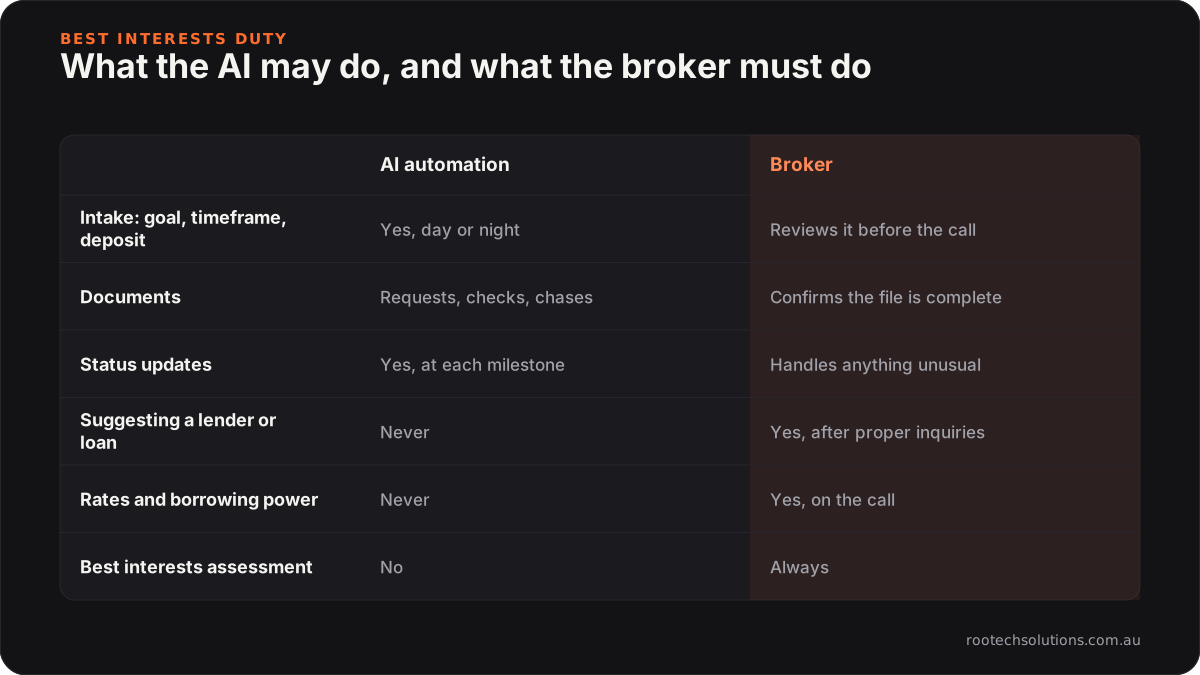
Caption: Keep the AI on the admin side of the line and the compliance conversation gets much shorter.
Brokers engage in credit activities under an Australian credit licence or as a credit representative of a licensee, and RG 203 notes that licensees are responsible for the conduct of their representatives. Before anything goes live, have your licensee or aggregator compliance team review the scripts and the hand-off rules. A well-scoped build makes that review easy because the AI never strays into advice. We went deeper on borrower trust in will mortgage clients trust AI with a loan application.
Does my broker CRM already do this?
Partly. Broker CRMs and platforms such as Salestrekker and Mercury, with lodgement through tools such as ApplyOnline, handle the deal pipeline, fact-find records, lodgement and compliance files. Several include client portals for document upload and automated reminders. Check what your aggregator's package includes before paying for anything new; the right answer may be to switch those features on.
A custom AI integration earns its keep in the places those tools leave to you:
- replying in under a minute at 9pm and booking the call, rather than waiting for a form to be read in the morning;
- actually reading the uploads, so a cropped payslip or a bank statement missing a page is caught the day it arrives, not the day before lodgement;
- chasing in plain language over SMS until the file is complete, then writing the result back to your CRM.
It is the same pattern accountants use to stop chasing clients for tax documents, which we cover in automating tax document collection.
What does the build look like?
Most broker builds are live in two to four weeks at a fixed price.
- Week one: map your enquiry-to-settlement flow, the document list per borrower type (PAYG, self-employed, first home buyer), and the hand-off rules: any question about which lender, rate or product goes to you.
- Week two: build intake, the document agent and status messages; connect your calendar and CRM.
- Week three: compliance review of scripts, then testing on staged and real files.
- Week four: live, with every lead tagged by source so you can measure the payback above.
You stay in the loop on everything that is advice. The AI drafts nothing a borrower could read as a recommendation, and borrower documents are stored with access limited to your team.
When is it not worth it?
- You see five to ten enquiries a month, almost all from referrers who expect to talk to you, and you already reply within the hour.
- Your leads live in a spreadsheet rather than a CRM. Fix capture first or you will automate the leak.
- Your cash flow cannot carry two or three months of cost before the first extra commission arrives.
Frequently asked questions
Can an AI give borrowers a rate or a borrowing power estimate?
Recommending a lender or product is credit assistance, so that stays with the broker. Most brokers keep any numbers out of the AI entirely and use it to collect the details and book a call where the borrower gets a proper answer.
Is it safe to send payslips and bank statements through an AI system?
It can be, if the system is built for it: encrypted uploads, Australian hosting, access limited to your team and a clear retention period. Ask any provider those four questions in writing, and check the answers against your licensee's privacy and record-keeping requirements.
How do I prove the automation paid for itself?
Tag every lead with its source and whether it came in after hours, then compare settled loans from those leads against the build and running cost after six months. Without source tagging, the effect disappears into the lag between enquiry and settlement.
Will my aggregator allow a custom tool alongside their CRM?
Most brokers can connect outside tools through the CRM's integrations or by exporting and importing records, but each aggregator sets its own rules. Check with them before the build starts; we design around whatever access you have.
See where your loans are leaking
We build intake and document automation for brokers in Melbourne and, remotely, across Australia, at a fixed price agreed before we start. Book a free AI workflow audit and we will map your enquiry-to-settlement flow with you, find the steps costing you loans, and tell you plainly whether the payback works with your settlement lag. The audit fee comes off your first project.