AI for Mortgage Brokers: Will Clients Trust It With a Loan?
AI for mortgage brokers, honestly: what clients will and won't trust a bot with, where credit assistance stays human, and what a guardrailed build does.
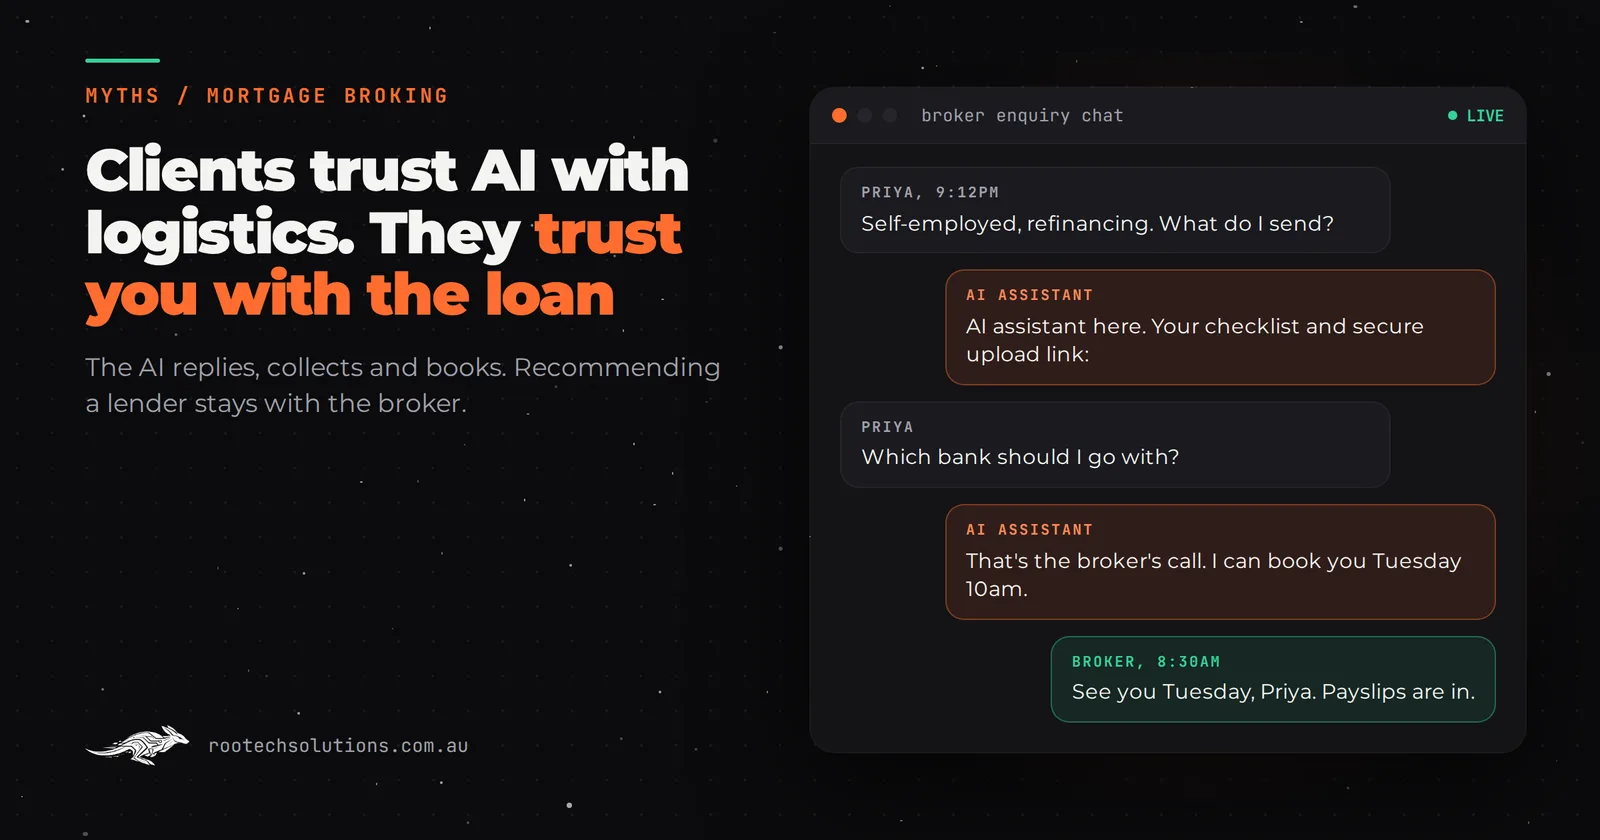
You've thought about AI for your mortgage broking business, and the same objection keeps stopping you: "My clients will never hand their payslips and their debts to a bot." Part of that fear is right. The part that's wrong is costing you the Sunday-night enquiries that go to whichever broker replies first.
Short answer: Clients trust AI for mortgage brokers with logistics, not advice. They are happy for an AI to answer at 9pm, send the document checklist, chase a missing payslip and book a call. They do not want it recommending a lender or explaining a decline. Build the AI so it never suggests a particular loan, keeps documents out of the chat, and hands every judgement to the broker.
What are clients actually afraid of?
Clients are not afraid of software. They already apply for credit cards online and upload ID to their bank's app. What they are afraid of is specific, and worth naming because each fear has a different fix:
- "A bot will decide whether I get the loan." They imagine an algorithm scoring them before a human ever looks.
- "My bank statements will end up somewhere they shouldn't." Fair, given how many data breaches make the news.
- "It will push me toward whichever lender pays the broker most." The trust problem brokers already fight, now with a machine attached.
- "I'll never get to talk to an actual person." Especially for self-employed borrowers, separated couples and anyone with a messy credit file.
Notice that none of these is "I don't want a fast reply." Borrowers want speed. They want it without losing the person who understands their situation.
Where is the fear right?
The fear is right about advice. Recommending a loan is not admin, and an AI should not do it.
ASIC's guidance on the mortgage broker best interests duty (RG 273) describes three stages the duty covers: gathering information about the consumer, assessing what credit assistance is in their best interests, and presenting recommendations with the reasons for them. It also notes that making a recommendation typically means suggesting the consumer apply for a particular credit contract, which is credit assistance. That sits with you and your licence. A chatbot that says "you'd suit Bank X's variable rate" is doing your regulated job, without your file notes, without your judgement and without your name on it.
The fear is also right about generic tools. A public chatbot that a client pastes their bank statement into is a real privacy problem, and a bot that improvises answers about borrowing power will eventually say something you would never put in writing.
Where is the fear wrong?
The fear is wrong about the front end of the pipeline. Most of what happens between the enquiry and the first proper conversation is not advice at all. It's logistics, and clients would rather it happened at 9pm than waited until Monday.
| Task | Fine for AI | Broker only |
|---|---|---|
| Reply to a Sunday-night enquiry within a minute | Yes | |
| Ask loan purpose, rough amount, deposit, employment type | Yes, as structured questions | |
| Send the document checklist for their situation | Yes | |
| Chase a missing payslip or rates notice | Yes | |
| Book the first call into your calendar | Yes | |
| Say which lender or product suits them | Yes | |
| Estimate what they can borrow | Yes, or a clearly labelled lender calculator | |
| Explain a decline or a valuation shortfall | Yes | |
| Handle separation, hardship or a credit default | Yes, AI flags and hands off |
The first five rows are where your hours go, and where your enquiries leak. The last four are why clients come to a broker at all. AI that does the top half well gives you more time for the bottom half.
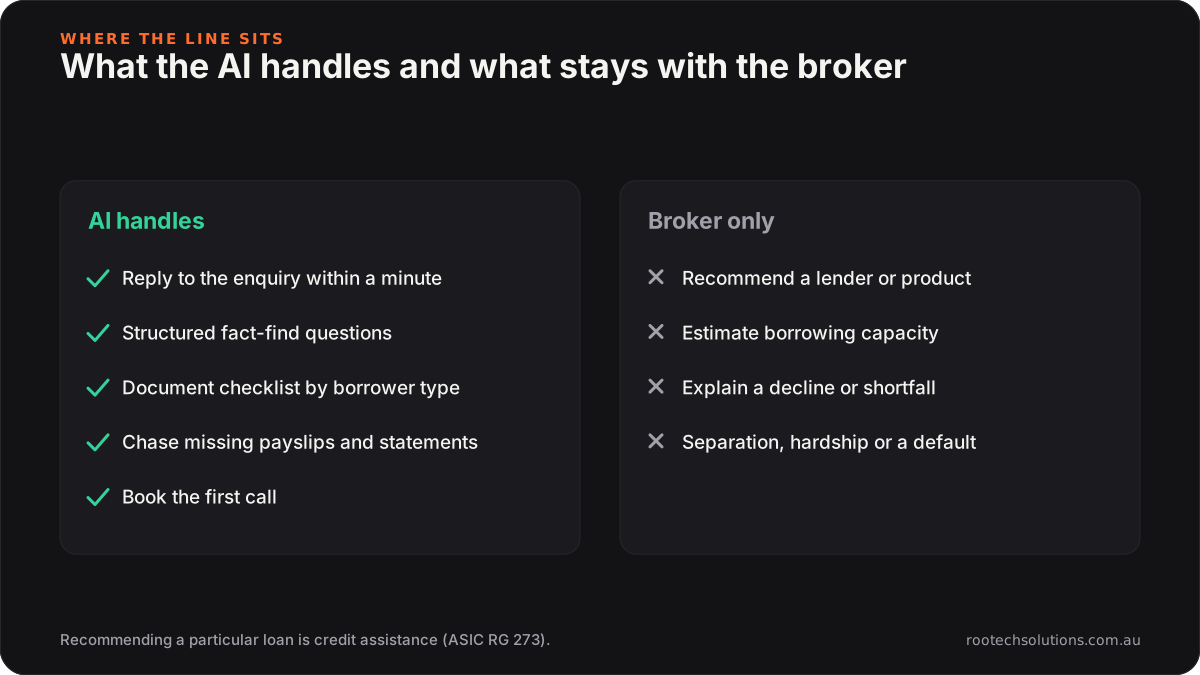
Caption: The line is credit assistance. Everything before it can be automated; everything after it stays with the broker.
What does guardrailed AI for mortgage brokers actually do?
A guardrailed AI answers from your approved material only, refuses to recommend, keeps documents out of the conversation and logs everything to your CRM. In practice:
- First reply and fact-find. The client fills in a short form or chats on your site. The AI asks the structured questions you would ask on a discovery call (purchase or refinance, rough amount, deposit, PAYG or self-employed, first home or not) and writes the answers into your CRM as a new lead.
- Document checklist by situation. A PAYG first home buyer gets one list; a self-employed refinancer gets another. The checklist comes from you, not from the AI's imagination.
- Secure upload, not chat attachments. The client gets a link to your existing secure upload or client portal. The AI tracks which items have arrived and sends polite reminders for what hasn't. It never needs to read the bank statement to know it is missing.
- Booking. It offers your next free slots and books the first call.
- Hard refusals. Asked "which bank is cheapest?" or "how much can I borrow?", it says that's a question for the broker, explains that the broker will compare options on the call, and offers to book it.
- Sensitive triggers. Words like separation, hardship, default or bankruptcy route the conversation straight to you with the chat attached.
It also tells the client up front that they are talking to an AI assistant. Clients forgive an AI that is honest and quick. They don't forgive one pretending to be you.
Is an off-the-shelf broker CRM enough, or do you need custom software?
For many brokers the CRM they already have is the right starting point. Aggregator-supplied CRMs such as Mercury, Salestrekker and MyCRM, and workflow tools such as BrokerEngine, already handle the deal pipeline, compliance notes and lodgement links. Check their current features and pricing; several have added automated reminders and client portals.
Where they stop is the conversation before the deal exists: the 9pm enquiry, the fact-find over chat or SMS, and chasing documents in plain English rather than with a templated email the client ignores. That gap is where a custom AI integration earns its keep. It sits in front of your CRM, writes clean leads into it, and leaves the CRM as the system of record.
Build custom only if the gap is real. A sole broker writing a handful of loans a month, who answers every enquiry within the hour, probably doesn't need it. A team that loses weekend enquiries, or spends hours a week chasing payslips, probably does. We set out the full cost case in what Melbourne mortgage brokers pay for AI automation, and compared a bot with a phone intake call in AI bot vs phone intake for mortgage brokers.
What does the build look like?
Most broker builds ship in two to four weeks at a fixed price, typically $3,000 to $6,000 depending on how many channels and integrations are involved. Running costs usually land around $150 to $450 a month once SMS, hosting and AI usage are counted. These are estimates; your enquiry volume moves them.
- Week one: your rules. Your fact-find questions, document checklists by borrower type, the phrases that trigger a handoff, and the list of questions the AI must refuse.
- Week two: the connections. Your website form or chat, SMS, your calendar and your CRM. Documents go to the secure upload you already use.
- Week three: testing on real enquiries. We replay past enquiries (anonymised) and try to make it give advice. It has to refuse every time before it talks to a client.
- Week four: live, with you watching. You review every conversation for the first fortnight and tighten the rules.
We're Melbourne-based and run these builds for brokers across Melbourne and remotely Australia-wide. The broker stays in the loop at every point that matters: the first proper conversation, the recommendation, the application, and anything the AI flagged.
How should client data be handled?
Keep the documents out of the AI and the AI out of the documents. The AI works with form fields and checklist status; the files live in your existing secure storage. Choose AI providers that don't train on your data, keep logs only as long as you need them, and write it down in your privacy policy. The Australian Privacy Principles are the yardstick to build against, and your licensee's compliance team should sign off on the data flow before launch. This is the same pattern accountants use for chasing tax documents, and it works for the same reason: the robot does the chasing, not the reading.
Frequently asked questions
Can an AI chatbot give a borrowing capacity estimate?
It shouldn't produce its own. If you want clients to see a number before the call, link to a lender's or aggregator's calculator that is clearly labelled as indicative, and have the AI say that the broker will work out a real figure. A number invented in a chat window is the fastest way to lose a client's trust.
Will clients be put off if they know it's AI?
Most borrowers care about getting a fast, accurate reply and a booked call. Tell them it's an AI assistant in the first message, keep it to logistics, and make "talk to the broker" one tap away. The clients who want a person straight away get one.
What happens if a client asks the AI which lender to choose?
It declines, explains that comparing lenders is the broker's job, and offers the next available call. That refusal is written into the build and tested before launch, because recommending a particular loan is credit assistance and belongs with the licensed broker.
Do I need to replace my broker CRM?
No. The AI integration sits in front of it and writes leads, notes and document status into it. Your CRM stays the system of record for compliance and lodgement.
Want to see where the line sits in your business?
We'll go through your last month of enquiries with you, mark what is logistics and what is advice, and show you what a guardrailed AI would take off your plate. Book a free AI workflow audit; the audit fee comes off your first project if you go ahead.